Bring the credit file through to review.
Risk OS connects financial analysis, credit memo review and exception handling, with the evidence ready for the authorised approver.
A clearer view of repayment capacity.
In this $7.50m term-loan request, an unsupported addback and omitted cash outflows overstate debt-service coverage. The finding follows the calculation into review.
The original memo recommends approval. The review traces its calculations back to the financial statements, debt schedule and lending policy.
In the original memo
1.92×$3.65m adjusted EBITDA ÷ $1.90m annual debt service
Includes a $0.30m unsupported addback and uses EBITDA as the coverage numerator.
After policy review
1.24×$2.35m cash available for debt service ÷ $1.90m annual debt service
Below the selected policy minimum of 1.25×.
The calculation behind the finding
$3.10m reported EBITDA + $0.25m supported relocation − $0.45m cash taxes − $0.55m maintenance capex = $2.35m cash available for debt service.
Two exceptions, with the evidence attached.
- Repayment capacity: 1.24× coverage against a 1.25× minimum.
- Customer concentration: 31% of revenue against a 25% maximum.
The credit officer receives the corrected analysis, policy references and open exceptions together, then decides the terms and conditions.
Case assumptions and source context
The application requests $5.50m to refinance existing term debt and $2.00m for growth capex; a $1.00m drawn revolver remains. FY2025 financials are assessed against proposed annual debt service of $1.50m on the term loan and $0.40m on the revolver.
The example uses policy C&I-2026.3, effective 1 July 2026. Financial statements are dated 31 August; the application and debt schedule, 2 September; and the original memo, 3 September. The proposed debt schedule is illustrative. The unrounded coverage ratio is 1.236842×.
This is an underwriting policy assessment. Existing loan covenants are tested against their signed terms and reporting periods.
The file, the memo and the next action.
The credit workspace
$2.35m of cash available for debt service produces 1.24× coverage against a 1.25× minimum.
Open full-size image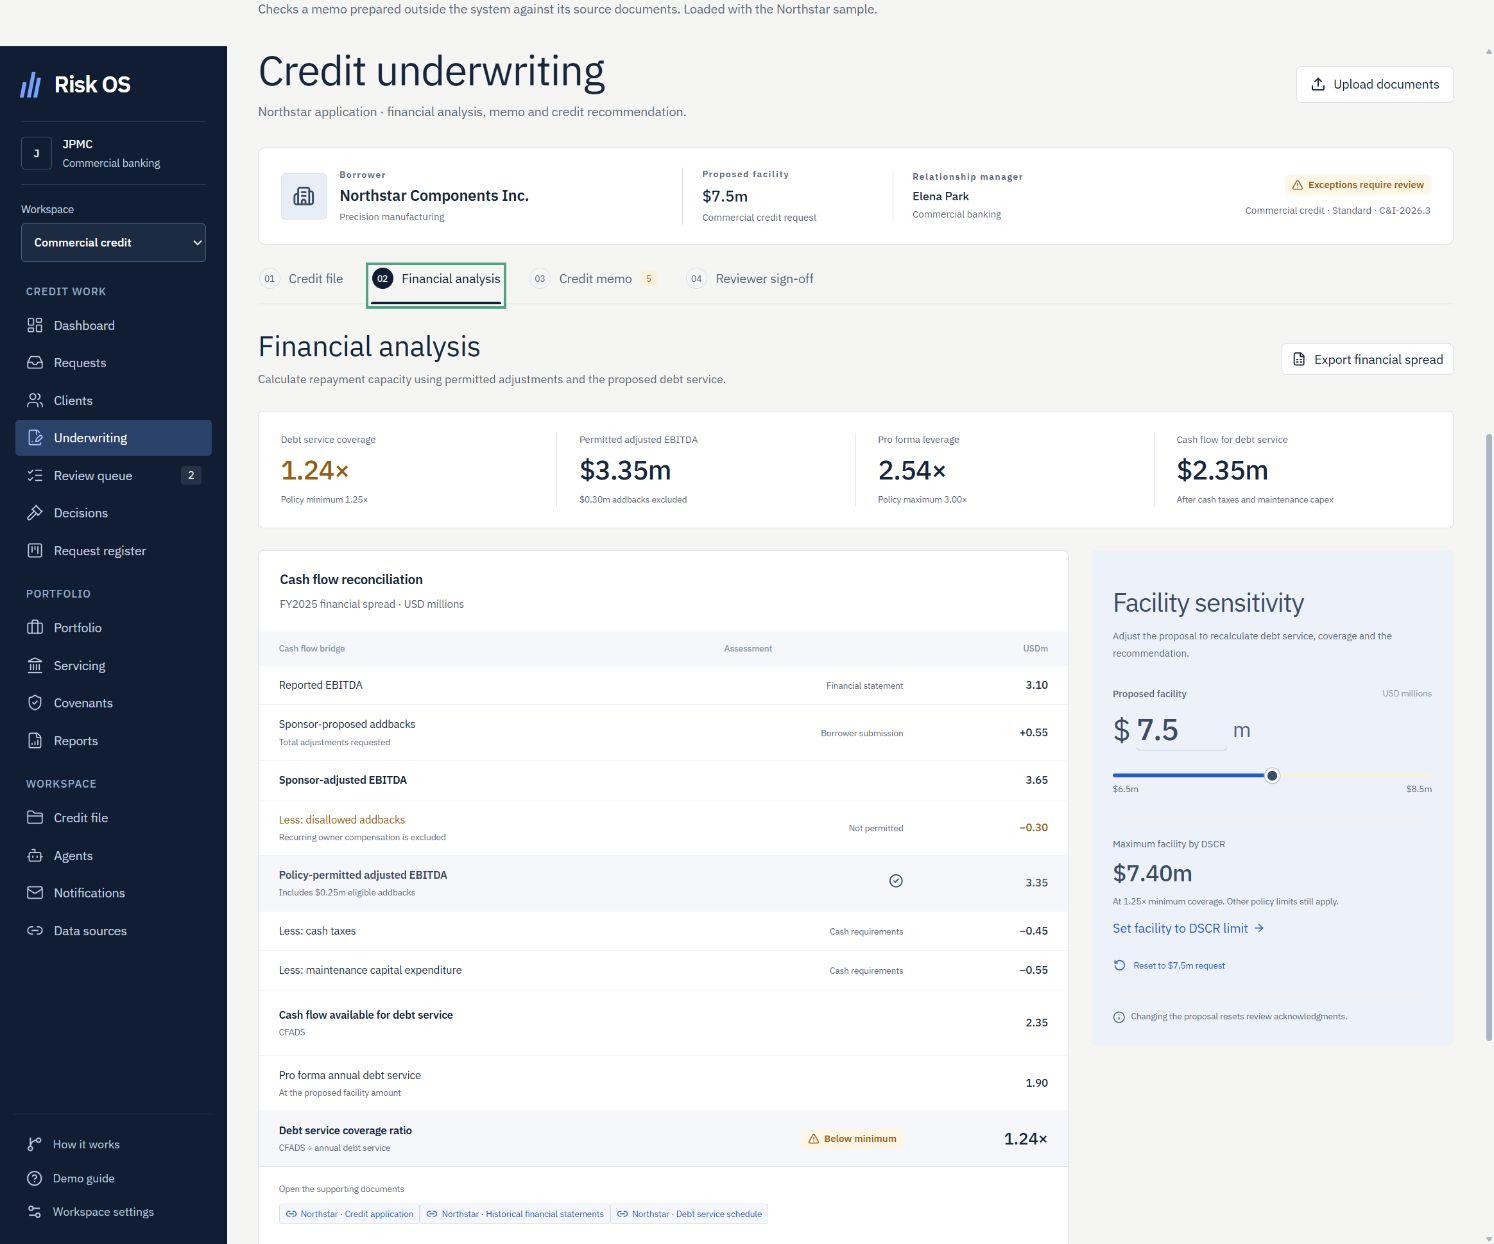
Across the life of a credit relationship.
Credit review and monitoring are the starting workflows. Explore the roadmap for conditions, recovery and portfolio-level work.
Prepare the borrower analysis, credit memo and exceptions for approval.
- Evidence & due diligence
- Credit assessment
- Memo & exception review
The credit workflow in 91 seconds.
From borrower evidence to a review package, with the finding and follow-up kept in view.
Start with the review your team needs to improve.
For banks, NBFCs and commercial lenders in India and the US, the first pilot starts with a defined credit task: financial analysis, memo review or borrower monitoring.
The pilot is scoped to the institution’s evidence, policy definitions and review authority.
Discuss a pilot